This week, the lithium battery new energy industry continues to be highly prosperous. Production scheduling data has reached a new high, mid-term results have been intensively realized, solid-state battery industrialization has accelerated, and the new consumption tax policy has entered a countdown. Multiple signals are intertwined, and the industry chain has ushered in a key node.
1. Industry data: Production schedule in August exceeded expectations, and energy storage became the first growth engine
In August, the total production schedule of China's lithium battery market was approximately 304GWh, a month-on-month increase of 7.4%, exceeding the 3%-5% range predicted at the beginning of the month. Among them, the scheduled production of energy storage cells is 125GWh, a net increase of about 10GWh month-on-month. The centralized stocking of large-scale overseas energy storage projects has promoted energy storage to become the first growth engine. In terms of power batteries, my country’s total sales of power and energy storage batteries in July were 185.2GWh, a year-on-year increase of 45.5%.
From January to July this year, my country's cumulative sales of power batteries reached 790.4GWh, a year-on-year increase of 37.1%, and cumulative exports were 146.7GWh, a year-on-year increase of 52.1%. The dominant position of Chinese companies in the global power battery market continues to be consolidated - in the first half of 2026, the total number of global power battery installations was 608.5GWh, a year-on-year increase of 20%, and the combined market share of seven Chinese companies reached 72.4%, a record high for the same period in history.
2. Policy dynamics: Countdown to the resumption of lithium battery consumption tax collection, differentiated tax rates guide industrial upgrading
There are only more than ten days left before the new lithium-ion battery consumption tax policy is implemented on September 1. The Ministry of Finance and other three departments have clarified that lithium-ion batteries will be levied a consumption tax at a rate of 2% from September 1, 2026, and will be raised to 4% from September 1, 2027; sodium-ion batteries, solid-state batteries, fuel cells, etc. will continue to be exempt from tax until the end of 2028. This is the end of the more than ten-year tax exemption policy for lithium-ion batteries since 2015.
"Step-by-step adjustments and classified policies" are the biggest highlights of the policy - giving the market a one-year buffer period and reducing the tax by half at 2%, while retaining a tax-free window for next-generation technology routes. Analysts pointed out that leading companies have the ability to pass prices to downstream companies, while companies with weak cost transmission capabilities are under greater pressure, which will accelerate the clearing of the industry and promote the concentration of share to the leader. Calculated based on the current mainstream market price, for a new energy vehicle equipped with a 60kWh battery, the cost of a single vehicle battery under a 2% consumption tax will increase by approximately 444-480 yuan.
3. Corporate News: The mid-term report results have been intensively realized, and production capacity construction has been accelerated
In terms of interim report performance, many lithium battery leaders this week handed over eye-catching report cards:
· Yiwei Lithium Energy's revenue in the first half of the year was 45.691 billion yuan, a year-on-year increase of 62.20%; net profit attributable to the parent company was 3.301 billion yuan, a year-on-year increase of 105.66%. Power battery shipments were 35.76GWh, and energy storage battery shipments were 44.46GWh, both achieving growth of more than 50%. The 46 series large cylindrical batteries have been mass-produced and supplied to BMW's new generation models.
· Tianci Materials’ revenue in the first half of the year was 14.71 billion yuan, a year-on-year increase of 109.28%; net profit attributable to the parent company was 2.861 billion yuan, a year-on-year increase of 967.91%, and energy storage battery electrolyte sales increased by more than 100% year-on-year.
· Xinzhoubang’s revenue in the first half of the year was 7.463 billion yuan, a year-on-year increase of 75.66%; net profit attributable to the parent company was 984 million yuan, a year-on-year increase of 103.33%.
· China New Airlines expects net profit in the first half of the year to be approximately 1.506 billion to 1.581 billion yuan, a year-on-year increase of approximately 100% to 110%. In the first half of the year, global power battery installed capacity was 31.2GWh, ranking fourth in the world, with a year-on-year increase of 39.5%.
In terms of production capacity construction, Tesla's Shanghai Gigafactory completed the 6 millionth battery pack off the production line; LG New Energy's factory in Lansing, Michigan, USA was officially put into operation, with an annual production capacity of over 35GWh; Goke Energy's Lanzhou New District 30GWh battery base phase one substation successfully delivered power.
In terms of strategic cooperation, CATL and Dongfeng Liuzhou Automobile signed a five-year strategic cooperation agreement, focusing on full-scenario technology research and standard customization. Hunan Yuneng submitted a listing application to the Hong Kong Stock Exchange and sprinted towards the "A+H" dual listing.
Another interesting news this week is that Evergrande Motors finally went bankrupt and liquidated. On August 20, the Guangzhou Intermediate People's Court ruled to accept the bankruptcy liquidation application of Evergrande New Energy Vehicle Investment Holding Group Co., Ltd., marking the complete end of the dream of this real estate giant that had spent huge sums of money on cross-border car manufacturing. Xu Jiayin has been sentenced by the Shenzhen Intermediate People's Court on suspicion of misappropriation of funds and other crimes. Evergrande Automobile has accumulated losses of more than 100 billion since its establishment, but has never been able to achieve mass production and delivery, becoming a negative example of the capital game.
4. Technology Frontier: The industrialization of solid-state batteries is accelerating in an all-round way
This week the solid-state battery track ushered in many milestones:
At the international standards level, the international standard proposal "Secondary Li-ion Batteries for Electric Vehicle Drives - Solid-State Battery Application Guidelines, Test Items and Conditions" led by my country was successfully approved by IEC. This is the world's first international standard in the field of solid-state batteries.
In terms of major projects, the advanced prismatic all-solid-state battery industrialization project was signed and settled in Suzhou Industrial Park. It is promoted by the Institute of Physics of the Chinese Academy of Sciences and China Science and Technology Low Carbon Cooperation. The first phase is to build a 0.2GWh battery cell pilot line and a 4GWh PACK production line. The target energy density is 400-600Wh/kg, and strives to achieve mass production in two years. The Dalian Institute of Chemical Physics' high-performance solid-state battery core material pilot platform project was announced, with a total investment of 55 million yuan and a planned annual output of 65 tons of core materials.
In terms of the pace of industrialization, 2026 is the first year of all-solid-state verification. GAC has started vehicle installation verification of hybrid solid-liquid batteries. CATL and BYD respectively plan all-solid-state small-volume production and demonstration installation in 2027. The cost of sulfide electrolytes has dropped by more than 35%, pushing solid-state batteries from "technically feasible" to "economically feasible." CITIC Construction Investment's research report pointed out that the current sector is in the triple resonance window period of "high production schedule + solid-state loading verification + equipment realization".
5. Market conditions: Lithium carbonate returned to 150,000 yuan, and sector sentiment recovered
The main contract of lithium carbonate futures stood at 155,000 yuan/ton this week, a significant rebound from the low of 143,000 yuan/ton at the end of July. The spot price of battery-grade lithium carbonate is about 151,000 yuan/ton. The stabilization and rebound of lithium prices has driven the collective strength of the lithium mining and battery material chains, and the CSI New Energy Vehicle Index has risen strongly.
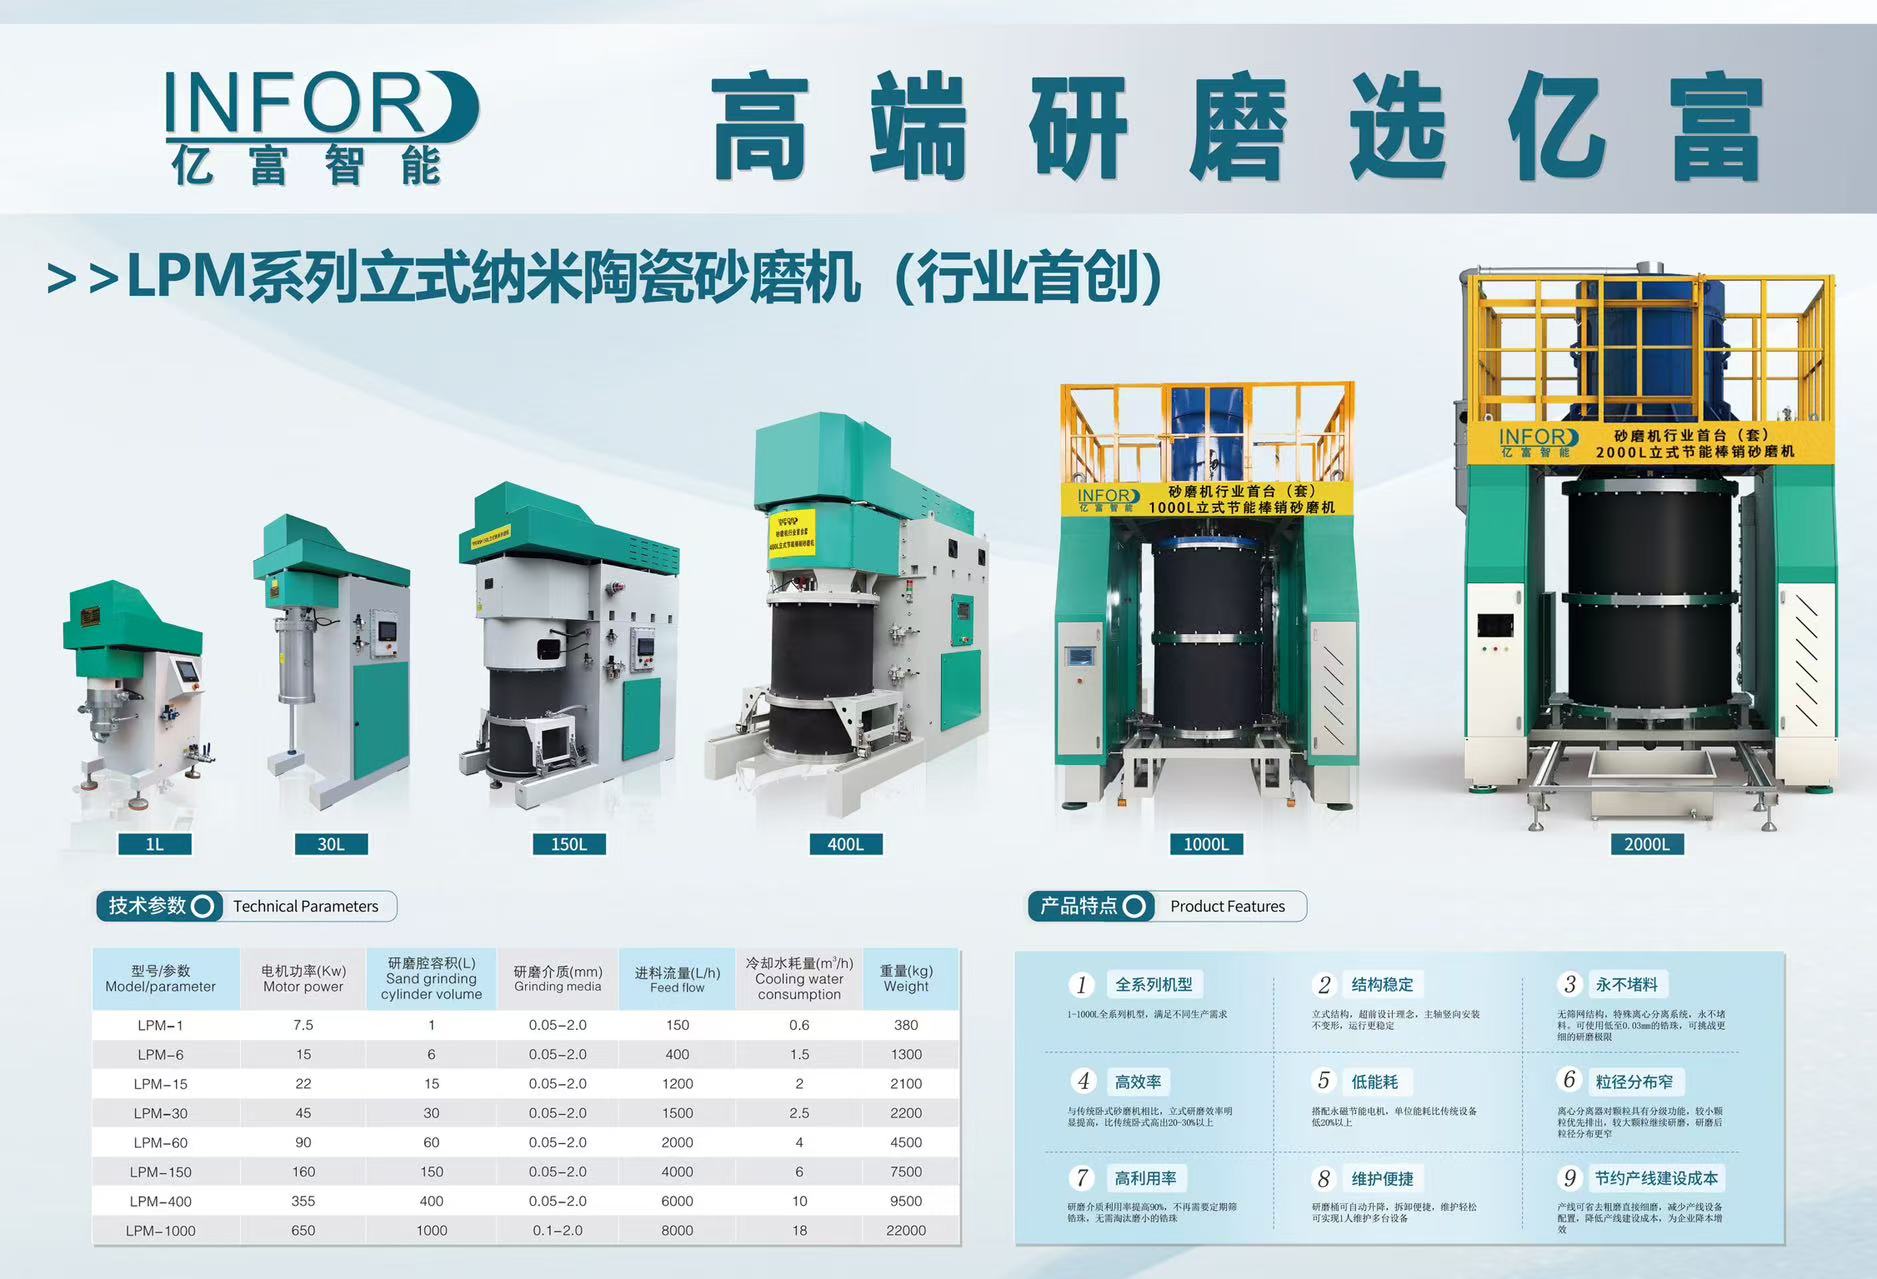
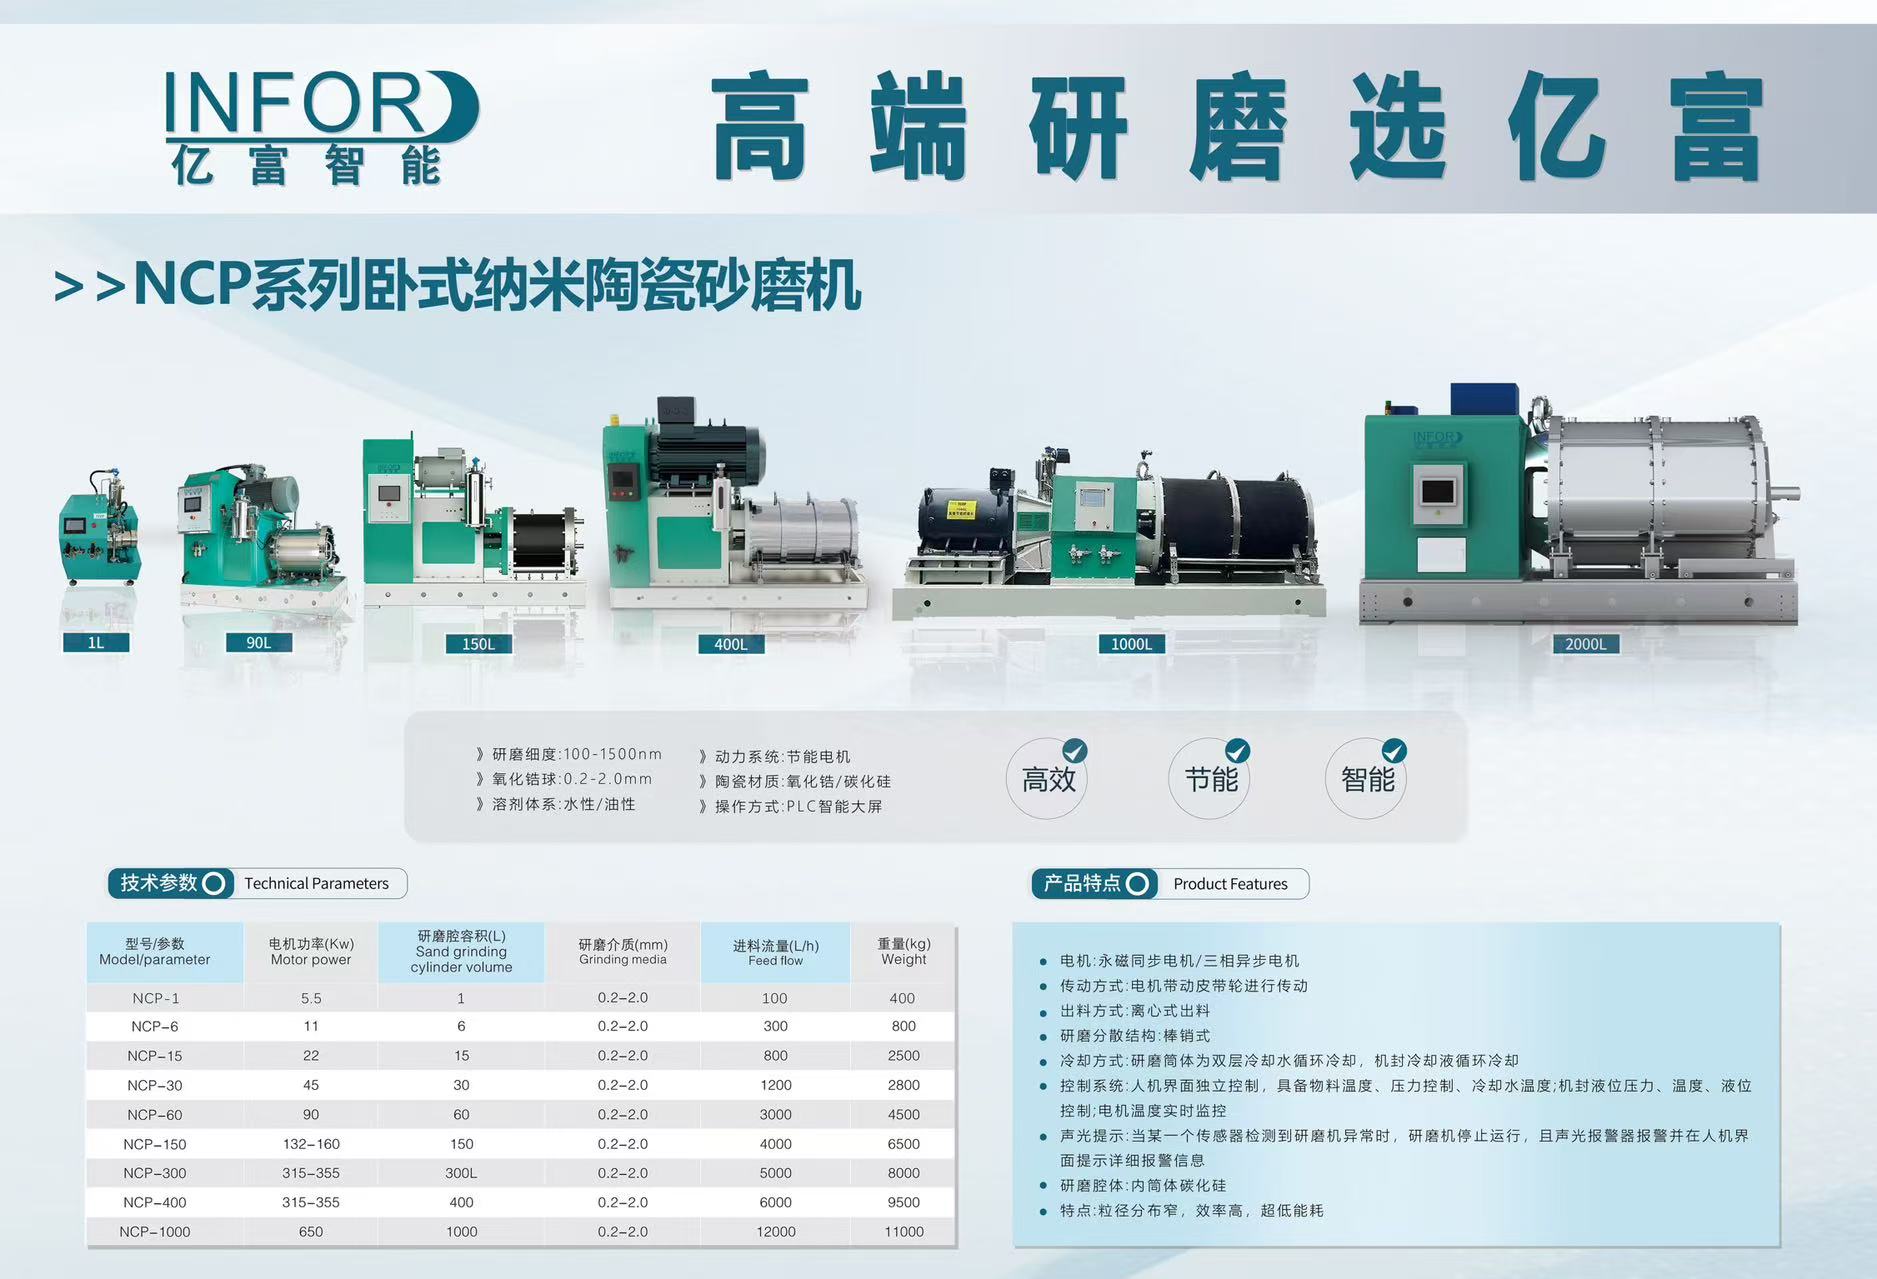
Summary of this week: August lithium battery production schedule reached a new high, mid-term results were intensive and exceeded expectations, solid-state battery industrialization accelerated across the board, and the new consumption tax policy entered the countdown - high prosperity and policy changes go hand in hand, and the lithium battery industry chain is standing at a key node in a new cycle. Energy storage has replaced power as the number one growth engine, solid-state batteries are accelerating from the laboratory to mass production, and the new tax policy will reshape the industry's competitive landscape. The traditional peak season of the Golden Nine and Silver Ten is coming soon, and the follow-up trend of the industrial chain deserves continued attention. The fall of Evergrande Automobile is in sharp contrast to the deep cultivation of Yifu, which once again proves that on the track of new energy with long slopes and thick snow, only solid technological accumulation and sound business strategies can make steady progress and overcome the cycle.

 English
 亿富机械
 +86-0769-85626082
 541476175@qq.com
 东莞市大岭山镇颜屋村莲颜路88号
